
Reports, outlooks and analysis from the ground
Our perspective on the projects, policies and opportunities shaping Africa, the Middle East, Southeast Asia and Latin America.
When your home market starts feeling smaller, it may be time to look beyond it

Shrinking demand. Tighter margins. Fiercer competition. Rising costs.
Perhaps your business doesn’t need a smaller ambition. Perhaps it needs a new horizon.
For many European companies, the commercial environment is becoming increasingly difficult. Markets covered by familiar free-trade and highly integrated economic frameworks can offer stability, predictable rules and sophisticated customers. But they can also bring something that is much harder to overcome: saturation.
- Your competitors are already there.
- Your customers have more alternatives.
- Operating costs are high.
- Labour is expensive.
- Procurement is increasingly competitive.
- Margins are under pressure.
And entering the same market as everyone else often means competing harder for a share of a market that is no longer growing as it once did.
So the question for an ambitious company is no longer simply: “How can we win more business in the markets we already know?” It may be: “Where is the demand that our competitors have not yet reached?”
Look beyond the familiar
Across Africa, the Middle East, Southeast Asia and Latin America, a different commercial picture is emerging. Not everywhere. Not without risk. And certainly not without challenges.
But in many markets, there are growing populations, industrialisation, infrastructure gaps, energy demand, digitalisation, healthcare needs, manufacturing expansion and rapidly developing consumer markets. And where demand is growing faster than local capabilities, opportunities emerge.
A European company with the right technology, expertise, quality, engineering capability or industrial know-how can sometimes find something increasingly difficult to find in mature markets: space to compete.
The first wall hides what is behind it
Emerging markets are rarely frictionless. Before reaching the customer, a foreign company may need to understand:
company formation · taxation · customs · licensing · standards · import procedures · local representation · procurement · banking · documentation · compliance · local partners · business culture · stakeholder relationships
For an inexperienced company, this can look like a reason to stay away. For an experienced international operator, it can become something else: a competitive barrier.
Once you learn how to navigate the market, establish the right local relationships and build a compliant operating structure, you may discover that many competitors never made it through the first wall.
The complexity premium
That creates what we call the complexity premium. You are not rewarded because the market is easy. You are rewarded because you can operate where others cannot.
The global industrial map is already telling the story
This is not merely a theoretical proposition. For decades, major Western companies have invested in emerging markets across manufacturing, energy, infrastructure, technology, consumer goods and industrial production.
Companies such as Siemens, Schneider Electric, ABB, GE, Bosch, Unilever, Nestlé and Volkswagen have established substantial international operations beyond their traditional home markets. Chinese companies have pursued the same logic at enormous scale. Huawei, Haier, Hisense, BYD, JAC, Sinopec and CRRC, among others, have built commercial and industrial positions across developing and emerging economies.
Why? Because international companies do not build factories, supply chains and long-term commercial operations simply because a market is easy. They go where they see:
demand + growth + strategic access + competitive advantage + long-term potential.
Manufacturing follows opportunity
When an international company establishes manufacturing capacity in markets such as Morocco, Egypt, South Africa, Kenya, Ethiopia, Indonesia, Vietnam or India, it is making more than a labour-cost decision. It is committing:
- capital
- technology
- management
- supply chains
- local employment
- infrastructure
- regulatory resources
- long-term commercial strategy
The equation can become particularly powerful when local demand + export potential + competitive operating costs + regional access + limited competition come together.
This is why an emerging market should not be judged simply by how difficult it is to enter. The better question is: what is the opportunity on the other side of the difficulty?
From market anxiety to market strategy
You do not have to abandon your existing markets. You do not have to move your entire company abroad. And you do not have to take unnecessary risks. You can start with something much simpler:
- Identify the right market.
- Test the demand.
- Understand the barriers.
- Find the right local partner.
- Enter selectively.
- Develop the market.
The objective is not to replace your existing business. It is to create another growth horizon.
This is where Connectivity comes in
Connectivity helps companies move beyond the familiar and evaluate where their next international opportunity may exist. We combine:
- Market intelligence
- Market entry strategy
- Partner and distributor development
- Business development
- Trade and regulatory market access
- Business diplomacy
- International projects and tenders
- Supply chain and logistics
to help companies move from “We think there may be an opportunity” to “We understand the market, we know the route in, we know who to work with, and we know what to do next.”
Your next market may not be the easiest one
It may be the one where your capabilities matter most.
If your home market is becoming increasingly crowded, expensive or margin-constrained, perhaps the answer is not to compete harder in the same places. Perhaps it is time to look beyond the familiar.
Explore an emerging market with Connectivity.
Assess your market entry → Explore our markets → Talk to Connectivity →
↑ Back to all insightsNavigating the complexity: a framework for success in emerging markets
Your global expansion blueprint is flawless—in theory. It has succeeded almost identically in every western free market country. You have a superior product, a proven sales playbook, and cutting-edge CRM technology. Yet, in the high-growth markets of Africa, the Middle East, Latin America, and Southeast Asia, that blueprint often meets a frustrating reality: stalled deals, regulatory surprises, and local competitors who somehow move faster. This isn’t a failure of your product or team; it’s the predictable result of applying a centralized, one-size-fits-all approach to the world’s most nuanced and dynamic economies.
This is where traditional methods are not merely insufficient; they are a liability. We serve as your embedded navigator, closing the context gap. We operate at the intersection of your corporate objectives and the granular reality on the ground. Our role is to map the invisible: identifying the true decision-makers, anticipating regulatory shifts before they are published, structuring deals that align with local business customs, and mitigating risks that never appear on a standard due diligence report. We ensure your market entry or expansion is not a series of costly experiments, but a precise, informed, and culturally intelligent operation.
Acknowledging the potential of emerging markets is the easy part. The true test of leadership lies in navigating the inherent complexities that have historically deterred European firms. These markets are not simply “easier” versions of Europe; they are fundamentally different operating environments where the rules of engagement are fluid, and the risk vectors are multi-dimensional. Success demands a sophisticated, granular approach to risk management and a willingness to move beyond outdated business models.
1. Moving beyond the “subcontractor” mindset
The first and most critical evolution is in the business model itself. Historically, many European companies engaged with emerging markets as subcontractors—sourcing raw materials or cheap components to feed their European factories. This model leaves the European firm as a commodity buyer, vulnerable to price swings and with no direct line to the end consumer.
To succeed today, European firms must become solution providers and brand builders. This means shifting from simply selling a machine to a factory in Mexico, to providing the full-service package: installation, training, predictive maintenance software, and financing. It means moving from exporting unbranded intermediate goods to Vietnam, to co-branding with a local partner to build consumer trust.
- Example: A German engineering firm shouldn’t just sell pumps to a Brazilian mining company. It should offer a “water management solution” that includes the pump, IoT sensors to monitor efficiency, and a service contract for local maintenance. This elevates the offering from a price-based commodity to a value-based partnership, insulating the company from local competitors who can copy a product but cannot easily replicate an integrated ecosystem.
2. Mastering the art of financial navigation
Currency volatility remains the single biggest destroyer of margin in emerging markets. The Turkish Lira, the Argentine Peso, and the Nigerian Naira have all experienced dramatic swings that can turn a profitable Euro-denominated contract into a loss overnight. European CFOs can no longer rely on simple hedging; they must employ a multi-layered financial defense:
- Natural hedging: Where possible, establish local revenue streams to cover local currency costs. If you are selling in Kenya, explore sourcing packaging or services locally to create a buffer against Shilling depreciation.
- Specialized trade finance: Move beyond standard bank letters of credit. Utilize instruments from development finance institutions (DFIs) like the EBRD, IFC, or AfDB, which often provide political risk insurance and currency stabilization guarantees for projects that align with their development goals. These institutions can de-risk projects in ways commercial banks cannot.
- Pricing in stability: Contracts should be structured with pricing tied to stable currencies (USD or EUR) or hard commodities (like gold price), with clear renegotiation triggers if the local currency moves beyond a certain band.
3. Embracing the “local first” talent strategy
The biggest mistake European companies make is staffing their emerging market operations with expatriates who attempt to replicate the Düsseldorf or Lyon office in Lagos or Jakarta. This creates a cultural bubble that misses local market nuances. The winning strategy is a “local first” approach: hire local leadership early and empower them. The role of the European expat should be to transfer corporate culture and technical knowledge, while the local team navigates the regulatory landscape, builds relationships with suppliers, and understands the consumer psyche. This isn’t just about goodwill; it’s about risk mitigation. A local manager knows which local officials are reliable and which contractors have a history of default.
From “global player” to “resilient enterprise”: the ultimate takeaway
When you combine a sophisticated approach to complexity with a genuine commitment to these markets, the transformation is profound. The company that once saw itself as a “European player with some exports” evolves into a truly “resilient enterprise.” This is the ultimate strategic prize.
The data from the Polish exporters is not an anomaly; it is a signpost for the future of European business. Those who diversified saw revenues grow by an average of 28% during turbulent times, while those who stayed home stagnated. This 28% is not just a revenue figure; it is a measure of resilience. It represents the buffer that allowed those companies to absorb the energy price shock of 2022, the working capital to ride out supply chain disruptions, and the confidence to invest in R&D when competitors were freezing budgets.
Scale, experience, and geographical diversification beget resilience. They create a virtuous cycle:
- Diversification generates higher growth, which provides the capital for investment.
- Investment in local markets builds deeper relationships, which insulates the company from political shifts.
- Deeper relationships generate on-the-ground intelligence, which allows the company to spot the next trend—or the next threat—before competitors who are reading about it in a Brussels briefing.
Waiting to be “big enough” to go global is a logical fallacy. You don’t get big in a stagnant market so you can afford to enter a growing one. You enter the growing one to get big—and more importantly, to build the financial muscle and operational agility to withstand whatever shocks the global system throws at you next.
In a world where the old certainties of transatlantic trade are crumbling, and where the next decade will be defined by competition for resources and influence, a presence in Africa, Asia, and Latin America is no longer a “nice to have.” It is the new bedrock of corporate survival. The European companies that will lead the next generation are not the ones protecting their home turf; they are the ones building their “second map” today.
↑ Back to all insightsAll you should know about the Medusa submarine cable project
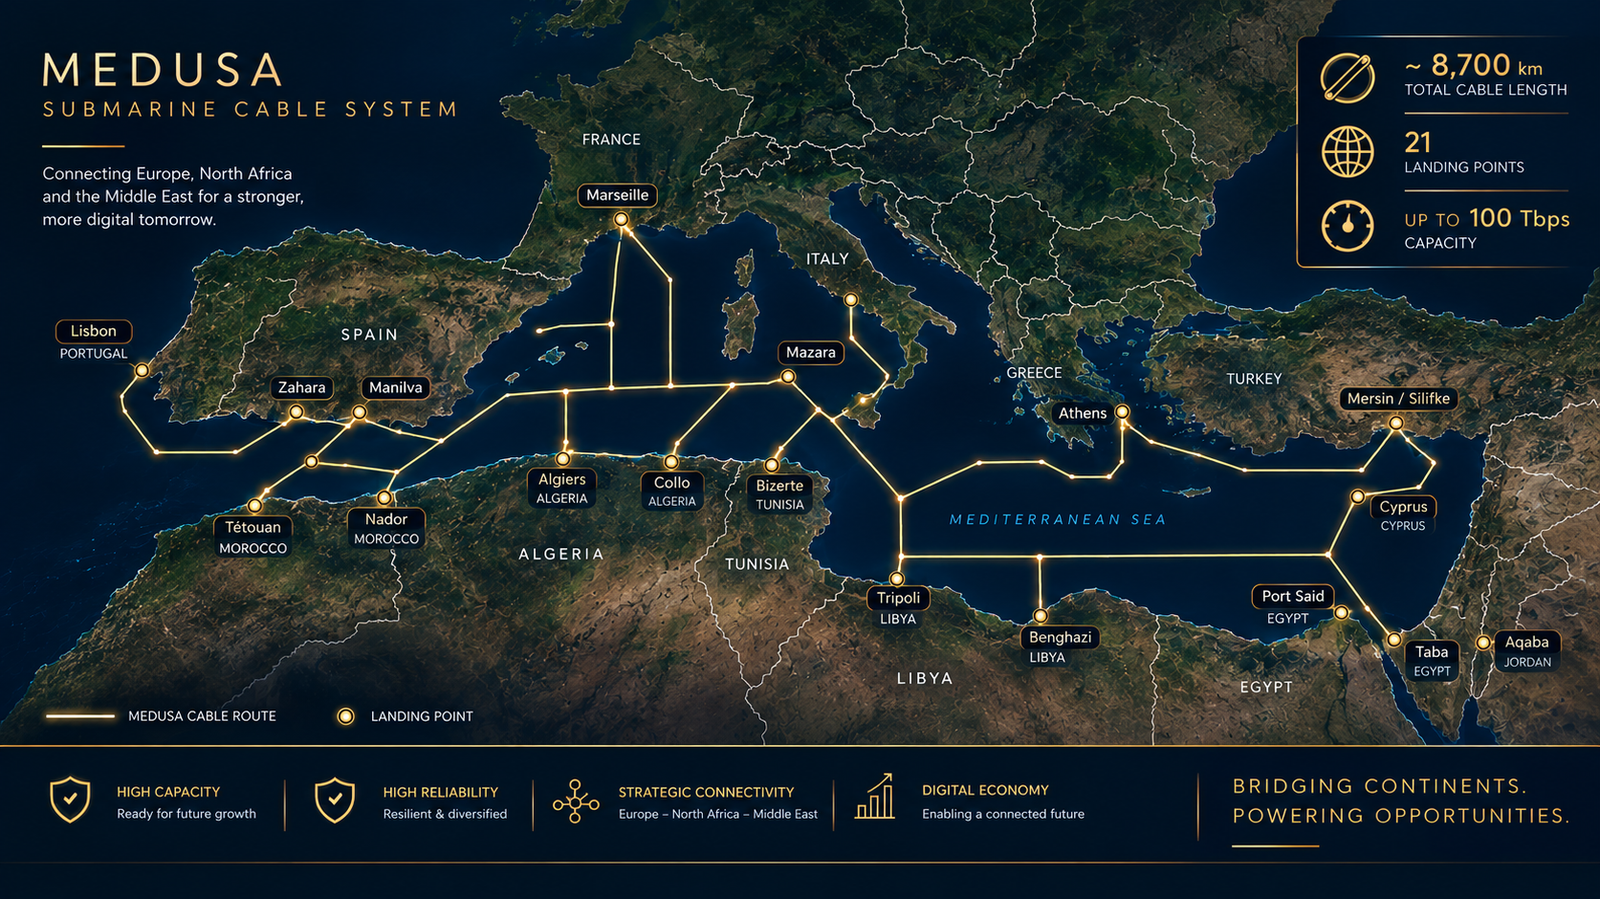
The Medusa submarine cable system is a massive, €342 million infrastructure project designed to create a new high-capacity digital highway across the Mediterranean Sea, fundamentally boosting connectivity between Europe and Africa. Led by the Barcelona-based telecom company AFR-IX Telecom, the project has strong backing from the European Union.
| Feature | Details |
|---|---|
| Project owner | AFR-IX Telecom |
| Total length | Over 8,700 kilometers |
| Total capacity | Up to 480 Terabits per second (Tbps) |
| Cost | €342 million |
| Key partners | Orange, Nokia, Tunisie Telecom, Telecom Egypt, and others |
| Expected operation | Early 2026 for the first phase, with full completion throughout the year |
| Key technology | Nokia’s 1830 GX platform and ICE7 coherent optics |
Route and landing points
The Medusa cable will feature 19 landing points across 12 countries, creating a ring-like structure around the Mediterranean and extending further. A later expansion is planned to extend the system down the West African coast to countries like Gabon.
Northern Mediterranean (Europe):
- Portugal: Lisbon (Carcavelos area)
- Spain: Barcelona and Zahara
- France: Marseille
- Italy: Mazara del Vallo (Sicily)
- Greece: Tympaki (Crete)
- Cyprus: Yeroskipou
Southern Mediterranean (Africa):
- Morocco: Nador and Tétouan
- Algeria: Algiers and Collo
- Tunisia: Bizerte
- Libya: Tripoli and Benghazi
- Egypt: Port Said (with onward connection via Telecom Egypt’s terrestrial network to the Red Sea)
- Future expansion: Jordan, Syria, and West Africa (e.g., Gabon, Democratic Republic of Congo)
Project status and key milestones
The project has moved from planning into an active deployment phase, with several major milestones achieved in late 2025.
- First landing (October 2025): The cable’s first landing was completed in Marseille, France, a major European digital hub. Orange played a key role in this operation.
- Tunisia connected (November 2025): The cable successfully landed in Bizerte, Tunisia, making it the first African country connected to the new system. Both Orange Tunisie and Tunisie Telecom are key partners for this branch.
- Morocco landing (December 2025): The cable landed in Nador, Morocco, with support from Orange Morocco and inwi.
- Completion timeline: The first segments (connecting France, Tunisia, and Morocco) are on track to be ready for service in early 2026. The remaining landings across the Mediterranean will be deployed throughout the year.
Significance and impact
The Medusa cable is more than just a new cable; it’s a strategic project with far-reaching implications:
- Enhanced connectivity: By providing a new, high-capacity route (up to 480 Tbps), it will significantly increase internet speed and reliability for millions of people.
- Improved resilience: It creates a diverse and redundant path for data traffic. If other cables are damaged, data can be rerouted through Medusa, enhancing the overall security and stability of the internet in the region.
- Digital sovereignty: For North African countries like Tunisia and Algeria, the cable offers a direct, high-capacity link to Europe, reducing dependence on infrastructure routed through other nations and strengthening their digital independence.
- Economic growth: The project is expected to spur investment in related sectors like data centers, cloud computing, and digital services, fostering economic development and job creation.
- Support for advanced tech: The high-capacity, low-latency link is crucial for supporting future technologies like 5G, AI, and the expansion of cloud infrastructure across the region.
- Connecting research and education: The project will also improve connectivity for nearly 500 education and research institutions in North Africa, linking them with their European counterparts.
Sources: SubTel Forum · Orange · Telecoms.com · Business Insider Africa · GÉANT CONNECT · Agenzia Nova · Developing Telecoms · SubTel Forum (Gabon) · SDxCentral
↑ Back to all insightsWhy no one is talking about the NEOM green hydrogen project
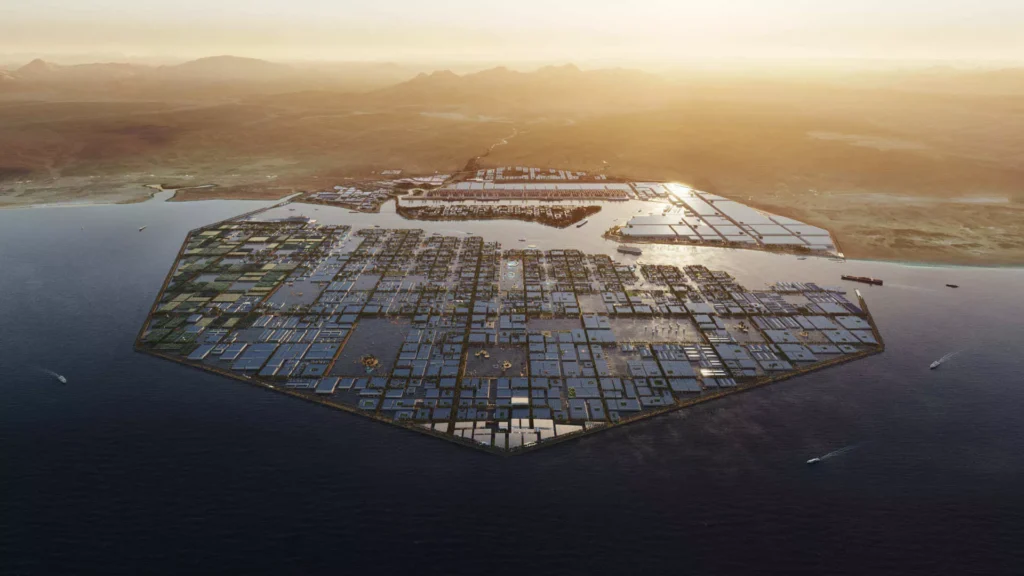
The project is a joint venture between three major players: Saudi Arabia’s ACWA Power, the U.S.-based industrial gas giant Air Products, and NEOM itself. The total investment for this first-of-its-kind facility is approximately $8.4 billion.
Technical specifications and scale
The project integrates massive renewable energy generation with advanced hydrogen production technology.
- Location: The plant is situated in Oxagon, NEOM’s advanced clean industries city on the Red Sea coast, which provides strategic access for exports. The supporting solar and wind farms are located approximately 80 km and 120 km away, respectively.
- Power supply: The entire facility will be powered by a dedicated 4 gigawatt (GW) renewable energy grid, combining solar and wind power.
- Production capacity: It will produce up to 600 tonnes of carbon-free hydrogen per day. This hydrogen will be converted into 1.2 million tonnes of green ammonia annually for easier transportation and global export.
- Key technology: The massive-scale electrolysis system, which splits water into hydrogen and oxygen, is based on technology from Thyssenkrupp. Air Products leads the engineering, procurement, and construction (EPC).
Current status and timeline
The project is advancing rapidly and is in its final construction phase.
- Construction progress: As of early 2025, the project had surpassed 80% completion across all its core sites. The solar and wind energy infrastructure is over 95% complete.
- Mid-2026: Completion of the 4GW solar and wind farms is expected.
- 2027: The facility is scheduled to begin testing and commissioning, with first commercial production of green ammonia expected by the middle of 2027.
Offtake agreements and market strategy
Securing buyers for this massive output is a critical component of the project.
- Primary offtaker: Air Products has a 30-year agreement to be the exclusive off-taker of all green ammonia produced at the facility.
- Key customer: A significant confirmed deal is with French energy company TotalEnergies. From 2030 to 2045, Air Products will supply TotalEnergies with 70,000 tonnes of green ammonia per year for use in its European refineries. This represents about one-third of the plant’s planned output.
- Sales strategy: To accelerate revenue, Air Products plans to initially sell the ammonia directly on the global market. They are also in the final stages of negotiating another major ammonia sales agreement with Norway’s Yara International for up to 1.2 million tonnes per year.
Economic and social impact
Beyond its environmental goals, the project is a significant economic driver for the region.
- Job creation: It is expected to create between 300 and 350 direct, highly skilled jobs. Furthermore, it is projected to generate a multiplier effect, creating six to seven times that number in indirect jobs within supporting industries and services.
- Workforce development: NGHC has already recruited much of its operations and maintenance staff and launched specialized training programs to prepare Saudi graduates for careers in the clean energy sector.
Sources: MOFCOM · Inspenet · Zawya · Saudipedia · Asharq Al-Awsat · Utilities Middle East · H2 View · PV Time
↑ Back to all insightsNo, Long Thanh International Airport is not going to be just a regular airport — rather a pivot hub in Southeast Asia
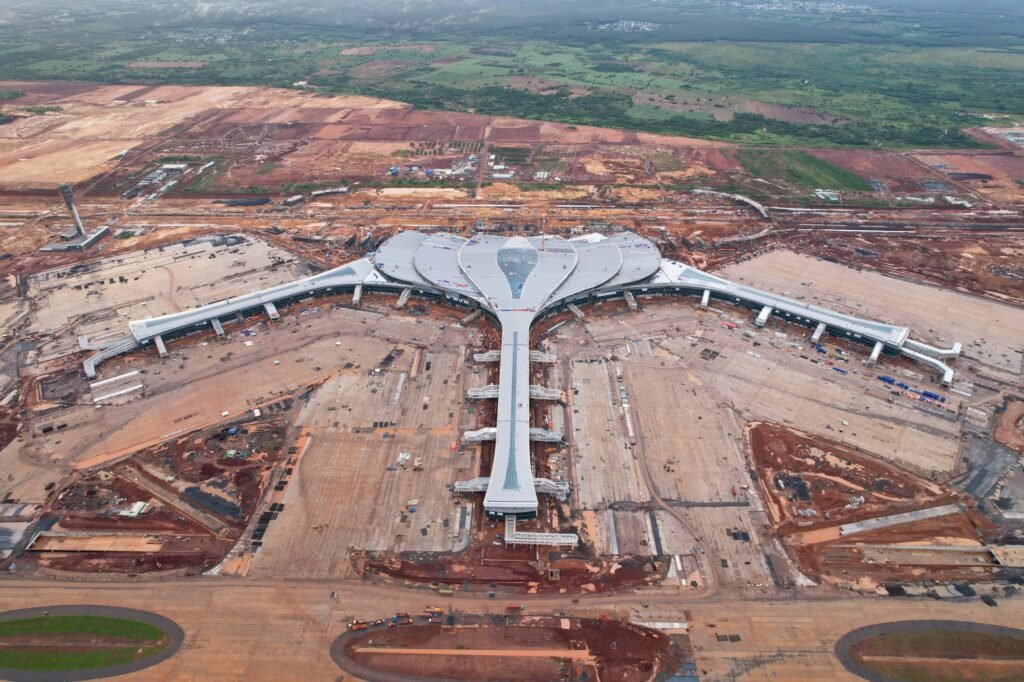
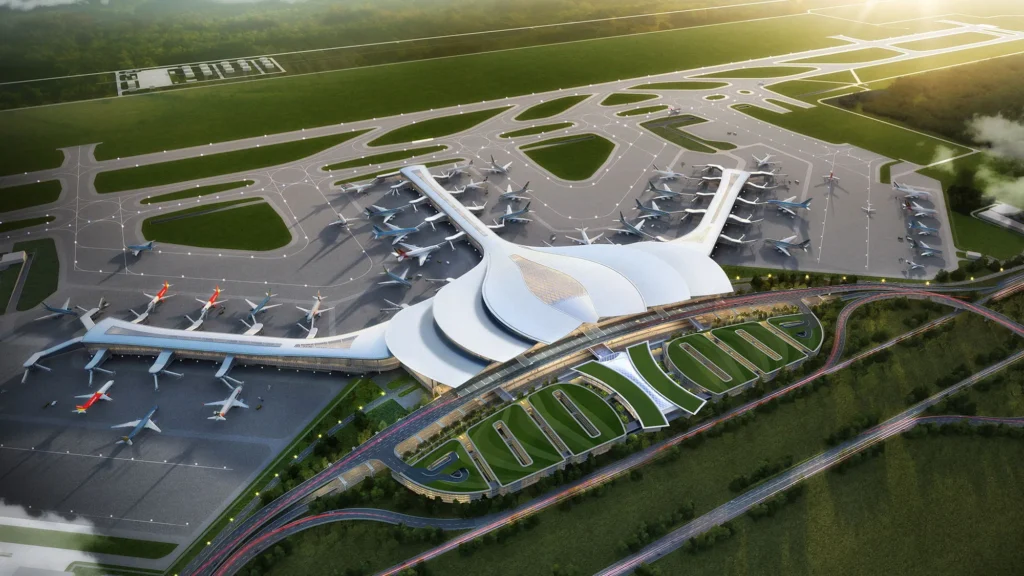
The project in numbers
| Feature | Phase 1 details | Full project (all phases) |
|---|---|---|
| Total investment | Over 109,000 billion VND (~$4.6 billion USD) | Nearly 337,000 billion VND (~$16 billion USD) |
| Project area | 1,810 hectares | ~5,000 hectares |
| Passenger capacity | 25 million passengers per year | 100 million passengers per year |
| Cargo capacity | 1.2 million tonnes per year | 5 million tonnes per year |
| Key infrastructure | Two runways & one passenger terminal | Four runways & four passenger terminals |
| Operational target | Commercial operations to begin by the end of June 2026 | Final phase target by 2045 |
Project timeline and current status
The project is being implemented in distinct phases, with the first nearing completion.
- Construction start: Work on Phase 1 officially began in 2020.
- Milestone reached: The project’s first flights (testing/inaugural) landed in December 2025.
- Urgent directive: In late February 2026, the Prime Minister issued an urgent directive for all units to complete Phase 1 in the first half of 2026. The goal is to begin commercial operations by the end of June 2026.
- Financial progress: By the end of 2025, unfinished construction costs for the Long Thanh project had reached VND 34,190 billion, a significant increase of over VND 21,400 billion from the start of the year.
- Enforcement: The government has emphasized strict accountability, stating that any violations affecting progress will be severely punished to avoid bottlenecks.
Connectivity and strategic role
Significant efforts are underway to ensure the airport is well-connected and fulfills its strategic role.
- Pressure on HCMC connectivity: Ho Chi Minh City is urgently accelerating connecting transport projects. Currently, travel from the city center can take over two hours due to reliance on congested highways. Key projects like the expansion of the HCMC-Long Thanh-Dau Giay expressway and Ring Road 3 are being prioritized for completion in 2026.
- Flight allocation strategy: Under the approved plan, Long Thanh is expected to handle about 80% of international flights, while Tan Son Nhat (HCMC’s current airport) will focus on short-haul domestic and regional routes.
- Regional ambitions: Once fully completed, Long Thanh aims to become a major international transit hub, competing with established airports like Singapore’s Changi and Bangkok’s Suvarnabhumi.
Future expansion (Phase 2)
Due to faster-than-expected growth in air travel demand, plans for the next phase are being accelerated.
- Accelerated timeline: Phase 2, previously scheduled for 2028-2032, is now being prepared for an earlier start. An early launch would allow the project to reuse labor and equipment from Phase 1, helping to cut costs.
- Phase 2 scope: This phase will include the construction of a third runway and a second passenger terminal, each designed to handle an additional 25 million passengers per year.
Sources: Vietnam.vn · Vietnam.vn (regional comparison) · Vietnam.vn (PM directive) · The Saigon Times · DTiNews · The World & Vietnam Report · Lao Động
↑ Back to all insightsSet your sights on the Grande Orientale iron ore in D.R. Congo — if you are in mining, you cannot unsee this
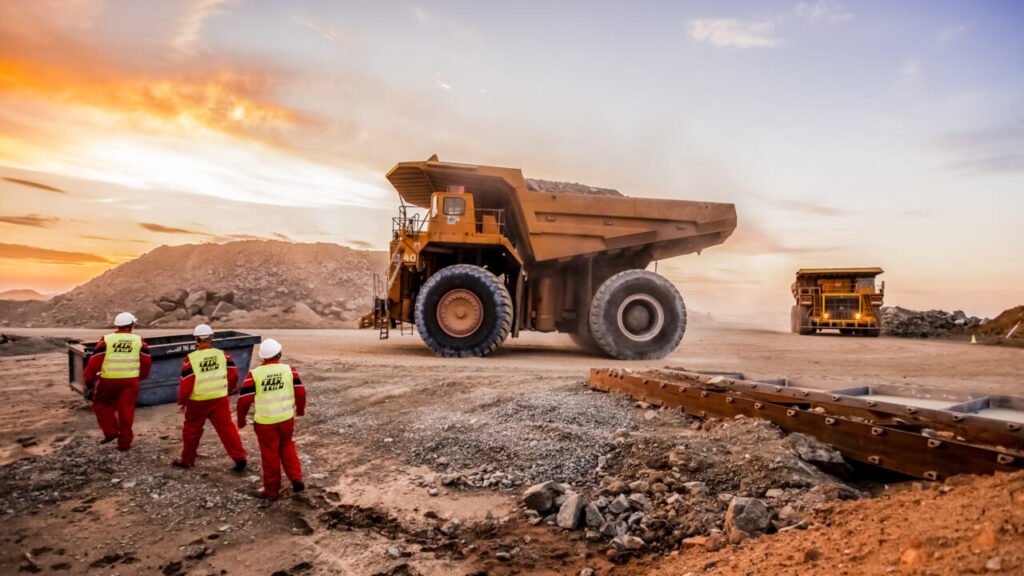
The Grande Orientale Iron Ore Project (MIFOR) in the Democratic Republic of Congo (DRC), based on the January 2026 government presentation.
Project overview and key numbers
| Metric | Phase 1 details | Full project / notes |
|---|---|---|
| Total investment (Phase 1) | $28.9 billion | Covers mining, processing units, and a multimodal logistics corridor. |
| Estimated iron ore resources | 15-20 billion tonnes | Located in the former Orientale province (Ituri, Haut-Uélé, Bas-Uélé, Tshopo). |
| Average ore grade | >60% Fe | Considered high-grade, similar to major global iron ore deposits. |
| Initial production capacity | 50 million tonnes/year | First phase target. |
| Potential expanded capacity | Up to 300 million tonnes/year | This would more than double the output of Guinea’s Simandou project. |
| Projected project horizon | 25 years | Operational lifespan for current economic modeling. |
| Projected cumulative revenue | >$679 billion | Over the 25-year horizon, based on “conservative market assumptions”. |
| Projected net cash flow surplus | ~$308 billion | Over the 25-year horizon. |
Project scope and infrastructure
The MIFOR project is designed as an integrated industrial and infrastructure complex, not just a mining operation. The $28.9 billion first phase includes:
- Large-scale extraction: Industrial mining of the high-grade ore body.
- Mineral processing: On-site industrial processing units to begin value addition within the DRC.
- Multimodal logistics corridor: A critical component to connect the landlocked northeast to global markets. This includes heavy-haul railway infrastructure, river transport on the Congo River, and access to the deep-water port of Banana, on the Atlantic coast.
Strategic importance and current status
- National strategy: The DRC government bills MIFOR as a “national economic architecture project” to diversify its economy beyond copper and cobalt, create long-term sovereign assets, and stimulate balanced territorial development.
- Financing interest: Authorities state the project has attracted interest from international institutional investors, though no specific names or binding agreements have been announced.
- Project governance: An expanded inter-ministerial commission has been established to oversee the strategic management and phased development of the project.
Key uncertainties and challenges
Several critical questions remain unresolved, as noted by multiple analysts:
- No feasibility study: The announced figures are not yet backed by an officially approved technical and economic feasibility study, which is a standard industry prerequisite.
- Resource vs. reserve: The use of the term “resources” rather than the more definitive “reserves” indicates the project is at an early stage, and the economic viability of extracting all the material is not yet proven.
- Financing plan: Details on the financing structure, the DRC government’s equity contribution, and the identity of potential private partners have not been disclosed.
- Implementation timeline: No official timeline or construction schedule has been published.
- Infrastructure challenge: Building a greenfield rail, river, and port logistics corridor on this scale in a remote region with limited existing infrastructure is a massive undertaking.
- Market context: The project was announced shortly after first ore shipments from Guinea’s giant Simandou project, which could add significant supply to the seaborne iron ore market and potentially pressure prices.
Sources: Zawya · The EastAfrican · Zoom Eco · GMK Center · Bankable Africa · ACP · Ecofin Agency · SteelHome
↑ Back to all insightsWant to act on these opportunities?
We help companies enter and grow in the markets behind these projects. We typically reply within one business day.